
- Benchmark ASINB0CY2NVP26
- MarketplaceUS
- Category ID335609011
- Analyzed Products
- Keyword14 inch laptop sleeve, padded laptop sleeve, fabric laptop sleeve
- Price Range-
- Minimum Net Profit Margin10.00%
- MOQ100
- Est. Purchasing CostNo price data
- Data Date2026-07-24
- Your Budget (for new listing) (CNY)¥500,000.00
Report summary from Keble AI Agent: Listing
结论很直接:这个市场不值得进入,已经是明显的过度拥挤+低利润价格战市场。 新品牌新品成功率是0%,近一年的57个新发布里没有任何一款达到可确认盈利;整体可识别盈利产品也只有2.27%,说明现在不是机会窗口,而是利润被彻底挤压的阶段。
Recommended Products Features Direction


These products have successfully captured market share and are profitable. Their design and features are suggested for your investment, based on market competition, saturation, and demand.
New Brands
VS
Old Brands
Green indicates better success rate, red indicates poorer success rate. If you are a new brand, focus on the left side; if you are an old brand, focus on the right side.
New Brands
Old Brands
#Budget Requirement
Listing结论很明确:这个市场不适合进入,用户预算也不够稳妥;它已经进入低成功率、低利润、强竞争的危险区。 仅看可识别利润的样本,市场整体盈利产品占比只有2.27%,新品盈利率是0%,而且2025年到2026年新品发布几乎全部是亏损或未成功,说明这不是成长型机会,而是价格战和资源战。
预算层面也不支持轻松入场。 用户预算是500,000 CNY,但可参考的新入场案例里,MoKo 的 B0GHXZTMS8 以22.99美元定价,账面利润率只有13.62%,仍然没有跑出稳定盈利;B0FVDT8QZ6 只有4.87%,几乎就是亏损边缘。kimhachan 更差,9个新品全部不盈利,像 B0FQ2G8TSS、B0FQ2HMQZR、B0FQ2KYS8B 的定价在48~53美元,但都没有销量结果支撑。反过来看,真正能赚钱的标杆主要是老品牌:tomtoc 的 B0C7CKDR1S 利润率22.14%,月收入约318,400,月销100;Osprey 的 B0C838HN8G 月销50、月收入约120,000,这类是大品牌打法,不适合作为小卖家模板。市场进入趋势也很差:2025年到2026年新品牌新品发布大批集中出现,但全部是非盈利,2026年1月单月就有12个新产品亏损,说明竞争在加剧,不是在变好。
小卖家更不应该进。 真正能当小商家参考的“新品牌成功案例”几乎没有;MoKo 作为新品牌里唯一能看到一点销量的样本,仍然只有50件/月、利润率13.62%,不足以证明可复制成功。相反,像 kimhachan 这类新品牌9个新品全失败,不能拿来做进入模板。若一定要看模型,大品牌应对标 tomtoc 的 B0C7CKDR1S 和 Osprey 的 B0C838HN8G;小商家唯一能勉强参考的是 MoKo 的 B0GHXZTMS8,但它也只是“勉强卖动”,不是健康成功。最终建议:不要进入。 这个市场是高风险价格战市场,小商家需要靠高强度营销甚至掠夺式打法才有机会,大品牌也不值得在当前条件下追加投入。
Early sourcing + logistics + marketing budget (USD)N/AExplains the budgetWith all these investments, who has profitable new releases
How many new listings are released by old brands?52.63%New listing success rate (old brands):0.00%New listing success rate (new brands):0.00%Alternatives- 普通无品牌超薄电脑内胆包/布质保护套:通常更便宜、款式更多,适合只想做基础防刮而不追求厚实缓冲的人。
- 通用平板/文件收纳袋:如果主要是把14英寸笔记本放进通勤包里,这类收纳袋往往更轻、更便宜,也更容易在文具店或电商平台买到。
- 带厚衣物/毛毯的自制缓冲包:用现有布袋或小收纳袋加一层毛衣、毛毯形成简易保护,几乎零新增成本,适合临时使用。
- 泡棉文件夹式保护套:外形像文件夹,价格通常低于专门的时尚布艺套,开合更直接,适合办公室和校园场景。
- 背包内置电脑隔层的通勤背包:如果用户本来就需要日常背负,这类产品可同时解决收纳和保护问题,减少再买一个独立电脑套的必要。
Alternative solutions may pose a risk to your investment in certain markets.
#Brands Investment Analysis
Listing这个市场不值得进入:已明显过度拥挤,而且正在走向价格战。 近一年里新品牌集中涌入,2025年出现32个新上新,2026年上半年又有22个新上新;但新产品里可确认盈利的比例是0%,全市场可确认盈利产品也只有2.27%,说明现在不是“有机会”,而是“大家都在拼命内卷但大多数都赚不到钱”。
证据很直接。 头部老品牌里,tomtoc 的 B0C7CKDR1S 是唯一能拿来参考的稳定赢家:售价25.69美元,月销50件,月营收1,284.50美元,利润率22.14%,上手早期投入约4,439.09美元,其中广告就占998.35美元;这说明大品牌要进来,至少得准备4,000美元级别的单品启动资金,而且还要承担持续投广告的压力。MoKo 作为新进品牌,B0GHXZTMS8 做到1705条评价却仍然不赚钱,B0FVDT8QZ6 甚至只有4.87%利润率、927条评价仍是亏损,属于典型的“高评价但低利润”陷阱;kimhachan 更差,9个产品全亏,9个新品无一盈利,单品 B0FQ2G8TSS / B0FQ2HMQZR / B0FQ2KYS8B 都是25%~31%表面利润率,但销量和收入都起不来,7条评价也没有换来成交。再看时间趋势,2026年1月到3月仍在连续冒出一批新货,但全部是非盈利,说明市场不是增长红利,而是在持续加剧的竞争和清仓式试错。
结论很硬:不要进。 大品牌这边,唯一能抄的是 tomtoc 的定位与产品结构:围绕MacBook/Surface的细分尺寸、轻薄防护、水阻、CornerArmor 这类功能卖点;但它的成功不是低成本能复制的,属于品牌和投放驱动。小商家这边,没有真正可信的成功样本,全部可见新入局案例都在亏损或接近亏损,而且评价数一旦超过200-300还不赚钱的,基本就是“predatory competitors”式打法,不是健康小卖家。
New products with Highest revenueMoKo
 Recent Monthly Revenue (USD):-(-)B0FVDT8QZ6 (4.7/5 (927 Reviews))Brand is a new entry in this marketNew ReleaseInsufficient Sales to Meet MOQUnderperformingNot enough sales volume to meet 100 MOQ
 Recent Monthly Revenue (USD):$1,149.50(50pcs/month)B0GHXZTMS8 (4.8/5 (1705 Reviews))Brand is a new entry in this marketNew ReleaseInsufficient Sales to Meet MOQUnderperformingNot enough sales volume to meet 100 MOQOld brand with the most profitable new products
tomtoc
 Recent Monthly Revenue (USD):$1,284.50(50pcs/month)B0C7CKDR1S (4.7/5 (124 Reviews))Brand is an old entry in this marketOld ReleaseSufficient Sales to Meet MOQOld ReleaseThis listing is deemed profitableMost investment in new productsLeast profitable new productsLeast investment in new products
kimhachan
Recent Monthly Revenue (USD):-(-)B0FQ2G8TSS (4/5 (7 Reviews))Brand is a new entry in this marketNew ReleaseInsufficient Sales to Meet MOQUnderperformingNot enough sales volume to meet 100 MOQ Recent Monthly Revenue (USD):-(-)B0FQ2HMQZR (4/5 (7 Reviews))Brand is a new entry in this marketNew ReleaseInsufficient Sales to Meet MOQUnderperformingNot enough sales volume to meet 100 MOQ
 Recent Monthly Revenue (USD):-(-)B0FQ2KYS8B (4/5 (7 Reviews))Brand is a new entry in this marketNew ReleaseInsufficient Sales to Meet MOQUnderperformingNot enough sales volume to meet 100 MOQ
#Differentiations
Unique productsCommon productsDifferentiation:- 粉米条纹+猫咪图案,视觉上最可爱、最吸睛
- |
- 复古布艺风与手提设计,风格辨识度高
- |
- 17英寸大尺寸,和常见纯色电脑套差异明显
B0FQ2G8TSS (4/5 (7 Reviews))Brand is a new entry in this marketNew ReleaseInsufficient Sales to Meet MOQUnderperformingNot enough sales volume to meet 100 MOQSales & BSR
Differentiation:- 真皮材质+彩色几何拼布,质感和外观都更特别
- |
- 轻奢商务风,与可爱布艺款形成明显反差
- |
- 适合MacBook用户,图像传达高端感,容易吸引点击
B07B528Q2Z (4.8/5 (1754 Reviews))Brand is an old entry in this marketOld ReleaseInsufficient Sales to Meet MOQOld ReleaseNot enough sales volume to meet 100 MOQSales & BSR
#Net Profit Margins: All vs New
Listing这个市场不适合进入:新品牌新产品盈利率为0%,整体可识别盈利产品只有2.27%,而且新产品里没有任何一款达到你要求的可接受盈利水平。 这不是一个适合小商家试错的市场,连大品牌也需要非常重的品牌力和投放才能勉强切入,且多数新入场者都在亏。
Profitability difficultyHigh Risk Due to Low Success RateAll products distribution on different profit levels
All products profit ratio distribution, including all products. For products with insufficient sales or missing profit ratio data, they will be categorized into other rows. This distribution included products that cannot determine the release date.
x < -10.0%-10.0% <= x < 0.0%0.0% <= x < 10.0%10.0% <= x < 20.0%20.0% <= x < 30.0%30.0% <= x < 40.0%x >= 40.0%otherNew products distribution on different profit levels
This are the profit ratios of all new products. There are products without sufficient sales, no more than 100pcs in 3 months, or no profit ratio data, or just released. Those will be considered as 'other'
x < -10.0%-10.0% <= x < 0.0%0.0% <= x < 10.0%10.0% <= x < 20.0%20.0% <= x < 30.0%30.0% <= x < 40.0%x >= 40.0%other#Top Products by Net Profit Margin
Top 20 Profitable Products
Most profitable products ranked by profit value. Only includes products with positive profitability and active sales, regardless of release date.
 B0CPJ4TN1XSmatree2023-12-06Yes$39.2850pcs$1964.031.04%$609.63B0C7CKDR1Stomtoc2023-06-08Yes$25.6950pcs$1284.522.14%$284.39
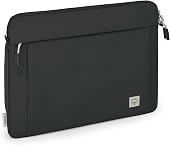 B0C838HN8GOsprey2023-06-14Yes$24.050pcs$1200.022.29%$267.48
Top 20 Non-Profitable New Products
New products with negative profitability ranked by lowest profit value. Only includes newly released products classified as non-profitable.
B0GHXZTMS8MoKo2026-01-21No$22.9950pcs$1149.513.62%$156.57 B0GMZTCDRStomtoc2026-03-02No$37.9950pcs$1899.532.67%$620.57B0FQ2G8TSSkimhachan2025-09-06No$53.0-pcs$-31.4%$-
 B0FNCTN73XSmatree2025-08-22No$39.89-pcs$-30.44%$-
 B0FRF7GXS1canvaslife2025-09-17No$17.38-pcs$-9.5%$-
 B0GLXRRT5BSmatree2026-02-06No$39.99-pcs$-28.36%$-
 B0GH4W5RX2Thule2026-01-16No$38.97-pcs$-32.16%$-
 B0FNRNWGXVSmatree2025-08-26No$49.06-pcs$-35.78%$-B0FVDT8QZ6MoKo2025-10-09No$21.99-pcs$-4.87%$-
 B0FQJH28VVcpnvwa2025-09-16No$31.99-pcs$-23.58%$-
 B0FNRK9WJ9Smatree2025-08-26No$49.99-pcs$-35.95%$-B0FQ2HMQZRkimhachan2025-09-06No$48.0-pcs$-29.82%$-
 B0B69NFTCRSwissGear2026-02-10No$34.46-pcs$-21.49%$-B0GH3RVVWYThule2026-01-16No$38.19-pcs$-23.64%$-B0GH5CCGZGThule2026-01-16No$38.72-pcs$-23.32%$-
 B0GKNR7G2WSooti Bandhan2026-01-30No$39.0-pcs$-21.66%$-
 B0B3BHH2JQSwissGear2026-02-10No$33.6-pcs$-22.45%$-
 B0FVKHYFXXcpnvwa2025-10-09No$45.99-pcs$-32.44%$-B0FQ2KYS8Bkimhachan2025-09-06No$53.0-pcs$-25.74%$-
 B0FK31GKQBSooti Bandhan2025-07-26No$39.0-pcs$-20.75%$-
#New Product Success Rates
Listing这个市场不适合进入,已经是明显的价格战/过度拥挤市场。 直接看结果:新品整体盈利率只有2.27%,新品盈利率为0.00%,而新品牌发布的新产品成功率也是0.00%;这不是“有机会”,而是“几乎全军覆没”的市场。
证据非常硬: 2025到2026年新品数量快速放大,2025年已出现32个非盈利新品,2026年又有22个非盈利新品,月度上从7月到次年6月持续有新品涌入,但没有任何新品盈利,说明市场不是在增长,而是在用更多上新把利润挤没。新品牌里,kimhachan 9个新品全亏,Thule 7个新品全亏,MoKo 2个新品全亏;老品牌里 tomtoc 3个新品只1个盈利、2个亏损,且新品盈利率仅33.33%,说明连老牌都只能勉强靠少数旧爆款撑住。更关键的是,唯一看到的“小品牌”式案例 kimhachan 9个新品全亏,根本不算真实成功;而Thule、tomtoc、MoKo都属于更偏大牌或有品牌势能的玩家,不是小生意可复制的样本。
结论和行动建议: 这里不值得做。大品牌即使进场也要准备明显高于单品基础预算的长期投入,且要对抗 tomtoc、Thule、MoKo 这类已有势能品牌;小生意没有看到合法、可复制的成功案例,反而更像被价格压到只剩低质竞争的战场。若一定要硬进,至少要能做出明显差异化、品牌化和长期投放,否则不要进入。
New products success rate.
What is the ratio of profitable products
Profitable (Unidentifiable released date)Profitable (Old product)Profitable (New product)Profitable (New product on old listing)New products but non profitableNo data availableNonprofitable new products divide by brands
What is the ratio of different brands owning all nonprofitable new products
SmatreekimhachanThuleOther#Success Rate by Entry Time
Listing这个市场不适合进入,已经进入过度拥挤的价格战区。 过去一年新品牌和老品牌的新发布几乎全军覆没:新品牌新发布盈利率是0%,全市场新发布盈利率也是0%,而且近几个月新增产品几乎全部是不盈利;这不是“还有机会”的市场,而是“进去就被卷”的市场。
证据很明确:2025年到2026年持续有新发布涌入,2025年新发布33个、2026年24个,但对应的成功记录全是0;月度上,2025年8月10个、9月11个、2026年1月12个新发布全部不盈利,说明进入越多,赢面越低。更关键的是,市场里只有2.27%的产品是盈利的,而新发布盈利率是0%;这意味着利润已经被极度挤压,利润率普遍低于10%的产品会成为主流的风险区。新品牌失败集中在 kimhachan、Thule、Sooti Bandhan、Smatree 等品牌身上,失败样本里 kimhachan 占33.33%,Thule 占25.93%,Sooti Bandhan 占14.81%,其他一堆品牌合计占25.93%,说明不是个别失误,而是整个赛道系统性失效。同时,成功案例几乎只剩老品牌支撑,比如 Osprey 的 B0C838HN8G 虽然只有154条评论却能做到盈利,说明要么靠老品牌势能,要么靠非常强的功能差异;普通新品牌没有这个条件。
对两类卖家都一样:大品牌也不该进,小商家更不该进。 大品牌若硬要进,至少要把 Osprey 这种老品牌案例当标杆,并准备高投入去做品牌、功能差异和长期补贴;但这类投入已经超出单个ASIN只覆盖前期备货、物流、推广的常规预算逻辑。小商家方面,市场里没有真正可复制的“小商家成功案例”;相反,很多新发布的评论量和打法更像强营销压制,不像自然成长。结论很直接:不要进入。 如果一定要做,只能选择拥有明显专利/技术壁垒、能显著区别于现有通用款的产品,否则很难跑出正利润。
How many products released each year
Y-axis is product counts. X-axis is time period. For each time period, there are 2 column, each column is a released type of a product. Columns are in following orders: New product, New product on old listing
How many products released each month
Y-axis is product counts. X-axis is time period. For each time period, there are 2 column, each column is a released type of a product. Columns are in following orders: New product, New product on old listing
#Net Profit Margins by Entry Time
Different profit ratios of products released in year
Header is the profit ratios and first column is different time period. Each cells includes how many products are relased at the specific timerange and has a corresponding profit ratios. Only profitable and with active sales (more than 100 pcs in 3 months) will be considered. Any products without sufficient sold units in 3 months will be marked as 'other'.
Time/Profit% x < -10.0% -10.0% <= x < 0.0% 0.0% <= x < 10.0% 10.0% <= x < 20.0% 20.0% <= x < 30.0% 30.0% <= x < 40.0% x >= 40.0% other 2022 0 0 0 0 0 0 0 0 2023 0 0 0 0 0 0 0 0 2024 0 0 0 0 0 0 0 0 2025 0 0 0 0 0 0 0 33 2026 0 0 0 0 0 0 0 24 ≥ 10% Profitable< 10% UnprofitableUnidentifiableDifferent profit ratios of products released in month
Header is the profit ratios and first column is different time period. Each cells includes how many products are relased at the specific timerange and has a corresponding profit ratios. Only profitable and with active sales (more than 100 pcs in 3 months) will be considered. Any products without sufficient sold units in 3 months will be marked as 'other'.
Time/Profit% x < -10.0% -10.0% <= x < 0.0% 0.0% <= x < 10.0% 10.0% <= x < 20.0% 20.0% <= x < 30.0% 30.0% <= x < 40.0% x >= 40.0% other 2025/7 0 0 0 0 0 0 0 4 2025/8 0 0 0 0 0 0 0 10 2025/9 0 0 0 0 0 0 0 11 2025/10 0 0 0 0 0 0 0 3 2025/11 0 0 0 0 0 0 0 3 2025/12 0 0 0 0 0 0 0 2 2026/1 0 0 0 0 0 0 0 12 2026/2 0 0 0 0 0 0 0 5 2026/3 0 0 0 0 0 0 0 3 2026/4 0 0 0 0 0 0 0 1 2026/5 0 0 0 0 0 0 0 1 2026/6 0 0 0 0 0 0 0 2 ≥ 10% Profitable< 10% UnprofitableUnidentifiable#Case Study
Success Casestomtoc Slim Laptop Sleeve for 14-inch MacBook Pro M5/M4/M3/M2/M1 Pro/Max 2026-2021, Water-Resistant Protective Case for 13.8 Inch Surface Laptop AI PC, Accessory Bag
This listing is deemed profitablePrice (USD)$25.69Released TypeOld Release (2023-06-08)Brand is an old entry in this marketSize and Weight35.0 x 25.8 x 3.3 cm, 180.00gProfitable Factors
Established brand with longevityBased on old ASINDistinct functions and featuresLow pricing strategyDesign & Appearance
深蓝色简洁商务风,偏向MacBook用户审美, 超薄纯色织物外观,带配件收纳位,整体更像轻量通勤收纳包而非普通套子Key Buying Motive
支持特定机型精确贴合,并集成配件仓,兼顾防护与收纳Target Customers
面向MacBook/Surface轻办公用户、需要同时携带充电器和线材的通勤人群Early Investment
Investment
Monthly Revenue (Recent) (USD)$1,284.5050 sold in the past 30 days · as of 2026年7月Net Profit Margin
Sea Freight18.95% / 22.14%Peak / Non PeakRail Freight- / -Peak / Non PeakAir Freight9.54% / 12.73%Peak / Non PeakSales & BSR Performance
Osprey Arcane 14 Inch Laptop Sleeve, Black
This listing is deemed profitablePrice (USD)$24.00Released TypeOld Release (2023-06-14)Brand is an old entry in this marketSize and Weight35.9 x 24.8 x 3.5 cm, 240.00gProfitable Factors
Established brand with longevityBased on old ASINDistinct functions and featuresDesign & Appearance
黑色极简风格,适合偏商务/通勤审美。, 极简扁平轮廓,带外部文件袋、通行带和侧边提手,外观更像轻便文件保护套而非普通软壳套。Key Buying Motive
除14英寸电脑主仓外,还提供外部文件/笔记本口袋,并支持行李箱穿带与侧提手,便于出差通勤。Target Customers
面向需要轻量化通勤收纳、同时携带笔记本电脑和文件的商务/学生用户。Early Investment
Investment
Monthly Revenue (Recent) (USD)$1,200.0050 sold in the past 30 days · as of 2026年7月Net Profit Margin
Sea Freight18.77% / 22.29%Peak / Non PeakRail Freight- / -Peak / Non PeakAir Freight8.23% / 11.75%Peak / Non PeakSales & BSR Performance
Loading samples... 67%